Nobody saves money by remembering to do it. People who build a cushion made the decision once, set up a transfer, and stopped revisiting it. A user logging into 1xbet lebanon to place a weekend wager already knows how this works, since every licensed bookmaker asks you to set a deposit cap before the session starts. Savings work on that principle too. Move the decision before the money moves, and discipline stops being something you need every morning.
Pick a Number Before You Pick a Strategy
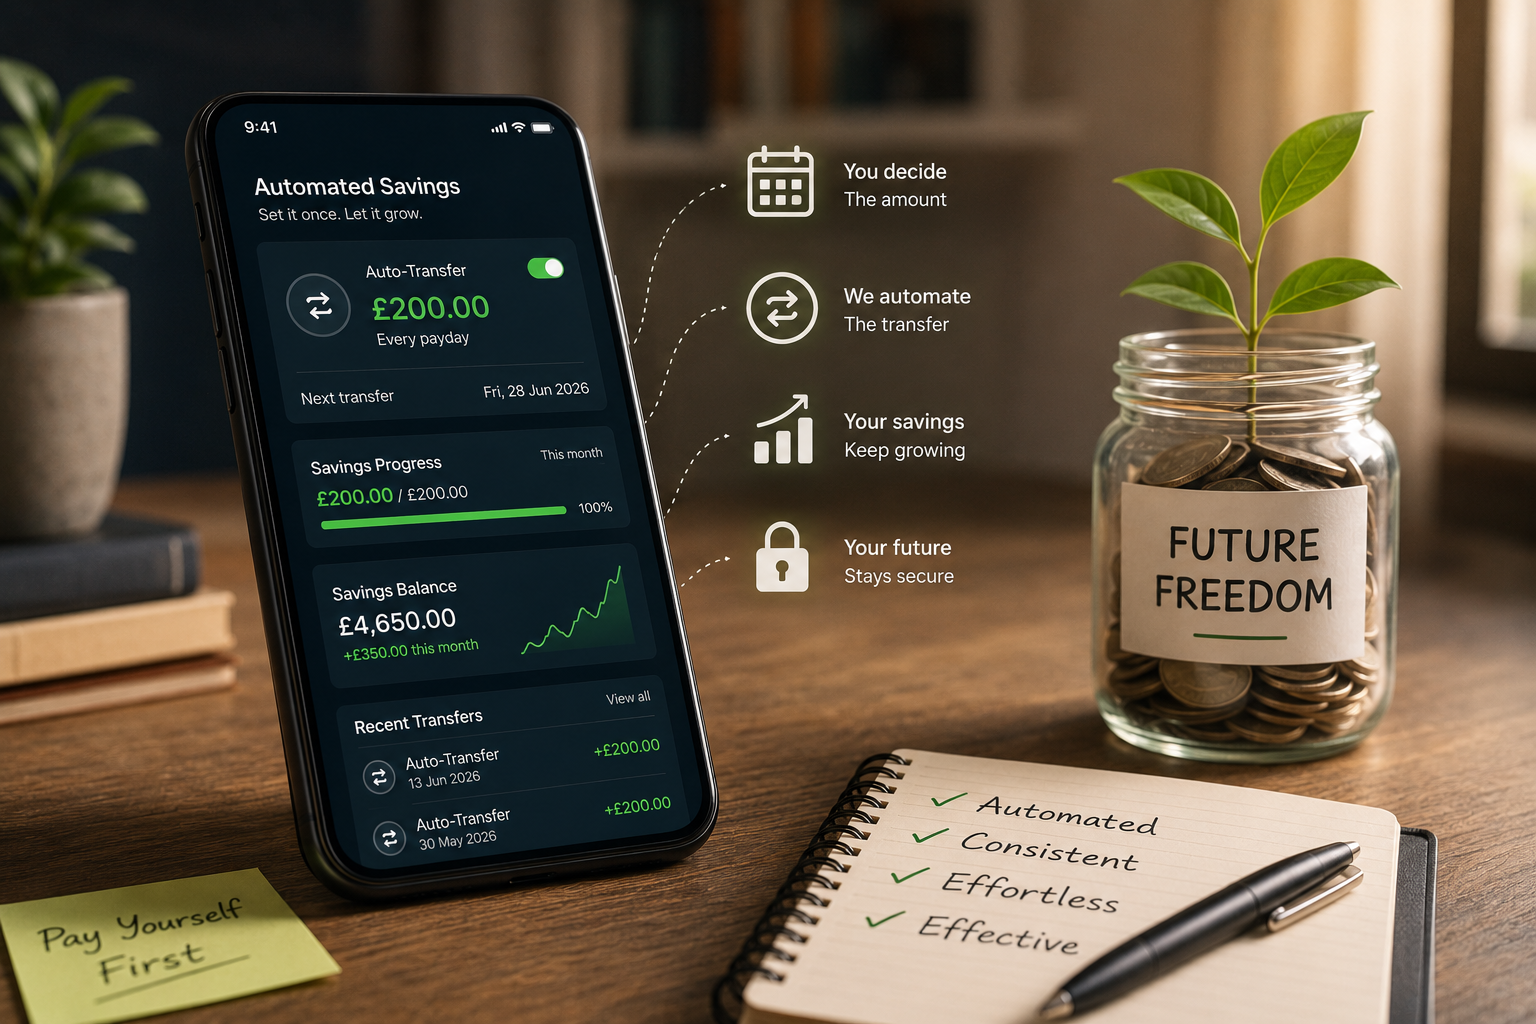
Most guides say budget first and save what remains. Whatever sits in the account at month’s end is usually close to nothing. Flip it. Decide on a fixed amount and move it out the day income arrives.
Pre-session deposit limits on betting platforms proved this years ago. A bettor who locks in a cap before the first market opens places sharper wagers than one adjusting mid-session. Session data backs it up, with pre-set limits linked to steadier outcomes and fewer regret-driven top-ups. Your savings transfer runs on that mechanic. Set the figure, schedule the date, let spending fit around what remains. Someone who moves 200 out of a 2,000 paycheck on day one lives on 1,800 and adjusts without thinking. Try saving 200 at month’s end instead, and you will find 40 left. The order of operations decides the outcome, and betting platforms learned that lesson before most banks did.
Round-Ups and Cashback Add Up Quietly
Round-up tools take every purchase and push the spare change into savings. Buy a coffee for 3.40 and 0.60 slides into a separate pot.
| Monthly spending | Average round-up | Estimated yearly savings |
| 1,500 | 0.35 | around 420 |
| 2,500 | 0.40 | around 580 |
| 4,000 | 0.45 | around 780 |
Sportsbook cashback programs discovered the power of micro-returns long before savings apps did. A percentage of every losing wager folds back into a bonus pot, loyalty points convert quietly, and the user barely notices the accumulation until it stacks into something worth using. Spare-change savings pots reached that destination from a different starting point.
How Bookmakers Taught Everyone About Tiers
Bookmakers do not apply one flat limit to every customer. They tier access based on behaviour and risk profile. Session wallets hold what a bettor plans to stake today. Reserve wallets sit behind a buffer. Withdrawal wallets carry a cooling-off period. That layered structure is worth borrowing for your own money.
- Tier one sits in a current account. Two weeks of expenses. Accessible instantly, earns nothing, exists to stop you from raiding the deeper layers.
- Tier two goes into a high-yield savings account. Three to six months of living costs. Earns around 4% at current rates. Takes a day to access, enough friction to block impulse withdrawals.
- Tier three locks away. Fixed-term deposit, workplace pension top-up, anything with a time barrier that keeps the money out of reach until you genuinely need it.
A quick look at how 1xbet organises its deposit and withdrawal layers shows why separation matters. Money that drifts between purposes disappears, and tiered systems exist to prevent exactly that.
Schedule It and Walk Away
A standing bet repeats a fixed stake at a fixed interval, and that repetition makes bankroll management predictable. Weekly savings transfers run on that logic. Smaller amounts feel less painful, the habit fires faster, and by the time you open your banking app on Monday, Friday’s transfer already left. You never saw it, never weighed it against a pair of shoes. Fortnightly works too if your income lands every two weeks, but monthly is the weakest option. Thirty days is long enough to convince yourself you can skip one round, and one skipped round turns into three.
Users who automate their deposit schedules on betting platforms report fewer impulsive top-ups. Bankroll management guides repeat what financial advisers have said for decades. Automate the outflow, and behaviour adjusts to the smaller number without the friction most people expect.
Let the Dashboard Do the Tracking
Budgeting apps that sync with your bank show where every pound goes. Categorised spending, weekly summaries, alerts when a category crosses a threshold. One study found that people estimate their subscription spending at roughly 86 a month while the real number sits closer to 219, and that gap only surfaces when a tracking tool lays it out in front of you. Sportsbook dashboards lay out wagering data with that kind of clarity. Bet history sorted by sport, session summaries broken by stake size, profit-and-loss updated in real time so nobody has to reconstruct the numbers from memory. When the data sits in front of you without effort, spending decisions sharpen and savings grow. Operators invested in these dashboards for a reason, and banks caught on.